SwiftlyMFS

The platform

Everything your MFI runs on, in one system.

From a client's first KYC document to write-off and recovery: lending, accounting, compliance, cash and the field work from one set of data.

One platform, not six tools

Record the loan once. The system does the rest.

When an officer disburses a loan or takes a repayment, SwiftlyMFS posts the journals, accrues the interest, applies your controls and updates the portfolio - with no re-keying and no reconciliation spreadsheet.

Repayment captured

USD 106.55

Loan
LN-000088 - Ropafadzo Masuku
Receipt
300149
Officer
Nyasha Mlambo, Bulawayo
  • Journal posted

    Cash in, loan balance down, interest earned.

  • Instalment settled

    The schedule and arrears are up to date.

  • Cash recorded

    Held against the officer until it is handed in.

  • Dashboards current

    Book size, PAR and officer reports.

Automate the routine.

Overnight, the system accrues interest, ages arrears, calculates provisions and prepares statements before your team arrives.

See your position live.

Portfolio at risk, book size, cash position and officer productivity are current all day, and every report line opens to the transaction behind it.

Grow without re-platforming.

Multi-branch, multi-currency and multi-country from day one, with each currency kept in its own books.

What changes when the routine work disappears

Fewer hands on each loan. More loans through the door.

Process more loans per officer.

Applications move through KYC checks, credit assessment and approval chains set by loan amount in one workflow. No email sign-offs, no paper routing.

Cut reconciliation to near zero.

Because every transaction posts itself to a balanced ledger, accountants review exceptions instead of rebuilding the books.

Catch problems while they are small.

Arrears aging and a daily collection sheet by officer show slippage today, not at month-end.

Close the month on schedule.

A guided period-close checklist covering FX revaluation, accruals and provisioning turns a multi-day scramble into routine.

If a task is repetitive, SwiftlyMFS already does it.

  • Accruals
  • Aging
  • Provisioning
  • Screening
  • Statements

One login, every function

A complete core system, not a loan tracker.

Six connected modules cover the whole institution, from a client's first KYC document to write-off and recovery.

01

Core Lending & Portfolio

The full loan lifecycle, from application to write-off.

  • Individual and group loans with flat, declining-balance, compound or effective-interest pricing
  • Rates quoted per day, week, month, quarter or year, independent of how often the borrower repays
  • Bespoke deals - any term in days, any number of repayments, bullet loans and uneven schedules - saved as reusable terms
  • Repayment schedules that respect your calendar and public holidays
  • Approval chains by loan amount, product and currency, with a second approver enforced
  • Arrears aging with daily penalty accrual or tiered penalties you define
  • Restructures, hardship relief, top-ups and exposure limits per client
  • Collateral and guarantors, with valuation history and loan-to-value cover
02

Accounting & General Ledger

Double-entry accounting that keeps itself.

  • Automatic posting - every transaction becomes a balanced journal entry
  • Your own chart of accounts, set up to match how you report
  • Multi-currency books with FX revaluation and period close
  • Trial balance, income statement and balance sheet that open to the source transaction
  • Manual journals and expenses with two-person approval and a full audit trail
  • Bank and mobile-money reconciliation with an unmatched-items queue

03

Compliance, Risk & Controls

Regulator-ready controls, built into the work.

  • Sanctions and PEP screening at onboarding, against the lists you load
  • Fuzzy-match scoring with a two-person clearance queue
  • Suspicious transaction reports, data-subject requests and consent records
  • Loan disclosure with borrower acknowledgement
  • Configurable interest-rate ceilings and affordability checks
  • Tamper-evident audit log that cannot be changed after period close

04

Reporting & Analytics

The right view for every audience.

  • Portfolio at risk and arrears by branch, officer, product and sector
  • Loan classification and provisioning to prudential standards
  • Executive, branch and officer dashboards - on the desktop and the phone
  • RBZ regulatory returns, including classification, large exposures and capital adequacy
  • Concentration and large-exposure analysis
  • Loan statements, settlement quotes and client-ready PDFs

05

Cash & Teller

Branch cash discipline, end to end.

  • Teller tills with opening floats and end-of-day cash-up
  • Strongrooms, and cash in transit between branches
  • Cash-up variances flagged, approved and posted to the ledger
  • Receipt books issued to each officer, with every number checked
  • Disbursement from cash, bank or mobile-money accounts
  • Cash position by branch and by currency

06

Client & KYC

Onboarding without paper.

  • Tiered KYC with document checklists and exposure limits
  • National ID validation for each country, with duplicate checks
  • Individual and group clients, with joint liability
  • A full client view: loans, arrears history, documents and credit score
  • Bulk import with a dry run before anything is saved
  • Data-subject requests and consent tracking

Built for the last mile

Your field officers don't stop when the signal does.

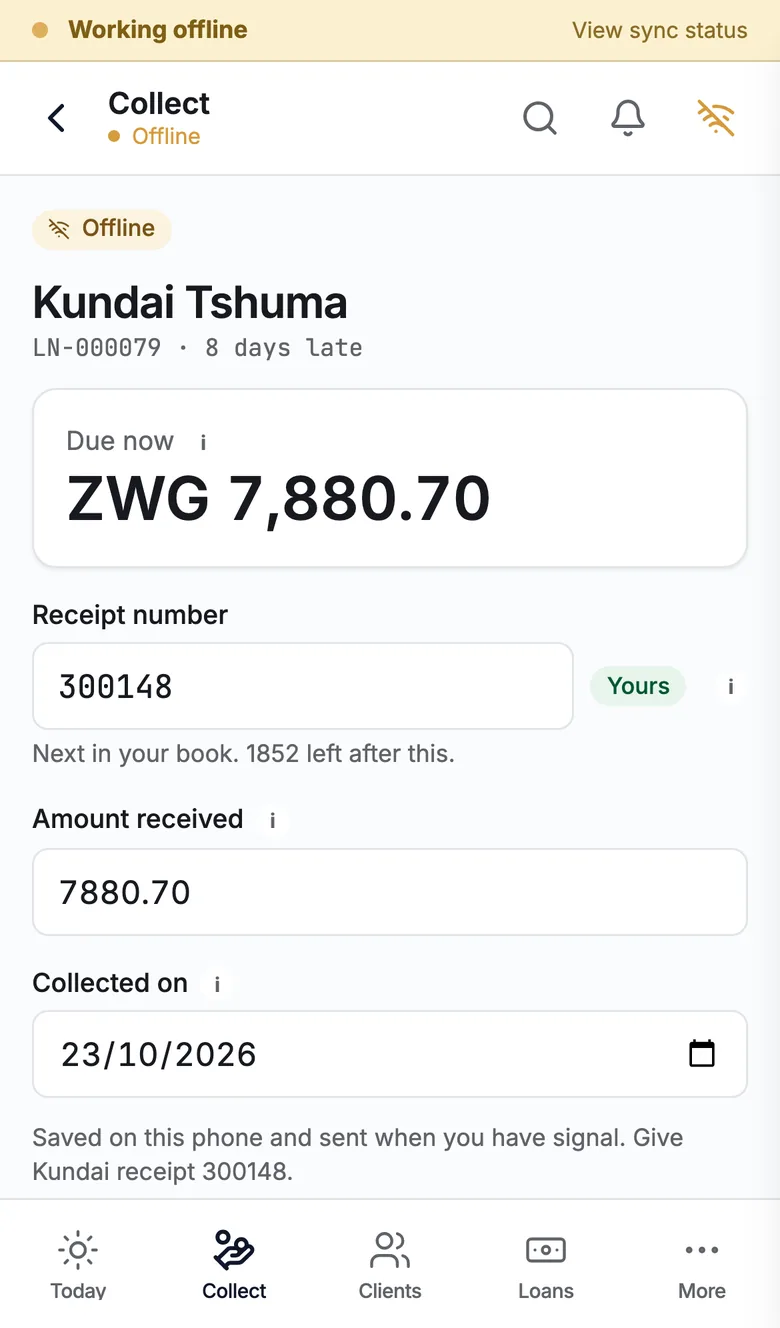
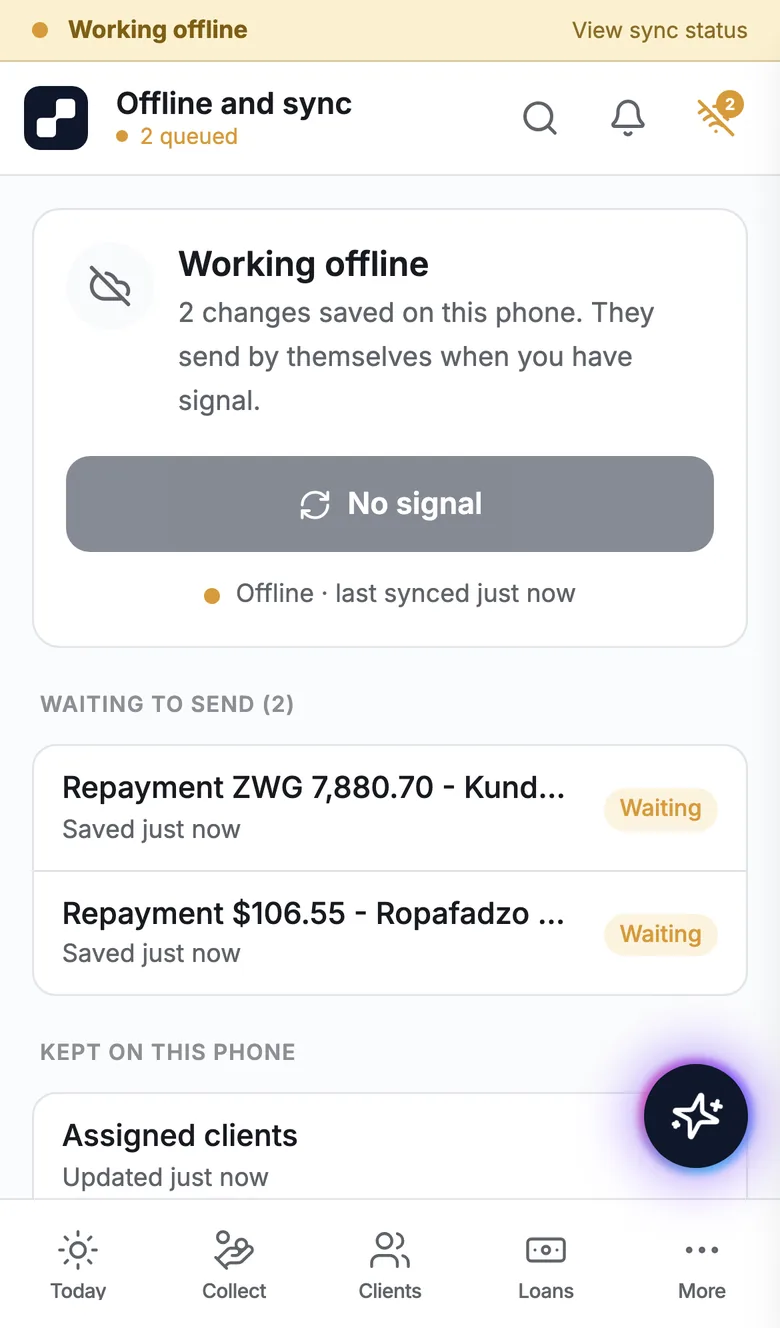
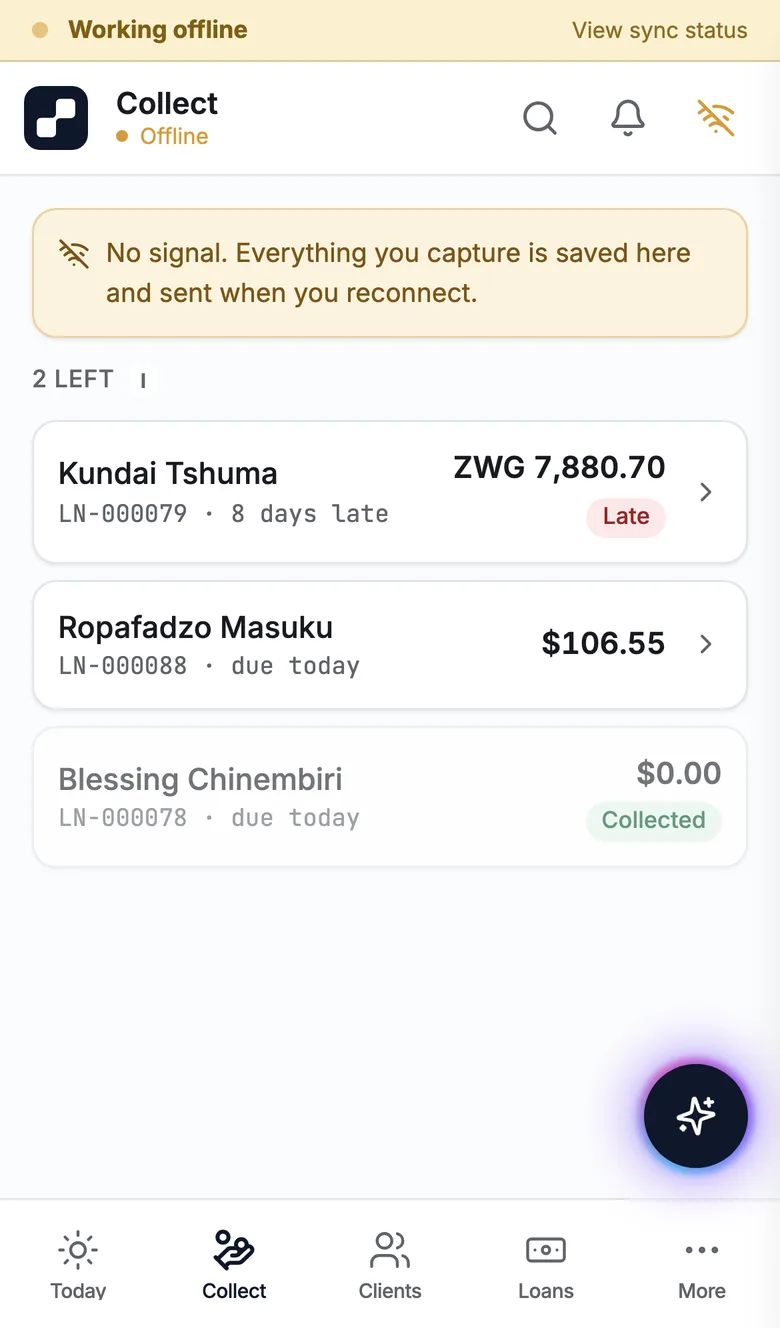
Officers keep working where connectivity is patchy: in the field, at a group meeting, deep in a rural ward. Everything they capture is held securely on the phone and sent automatically when the signal returns, with nothing lost and nothing posted twice.

  1. A loan officer's round with no signal: a note that everything captured is saved on the phone, and the stops still to collect.
    Work fully offline.Today's round, collections, new clients and loan applications all work with no signal.
  2. A repayment being captured with no signal: the receipt number is checked against the officer's book and marked as theirs, with the receipts left in the book.
    Receipts checked on the spot.Each officer's receipt books are on their phone, so a wrong or already-used number is caught before the borrower leaves.
  3. The offline and sync screen: two repayments saved on the phone, waiting to be sent when the signal returns.
    Sent automatically.Captures are encrypted on the phone and sent the moment the signal returns, never lost and never posted twice.

Runs on the phone they already have.

No app store and no special hardware. It installs from the browser on Android and iPhone.

Cash control in the field

Know where every collection is, from the borrower's hand to the vault.

Cash collected in the field is where microfinance institutions lose money. SwiftlyMFS ties every collection to a paper receipt, a named officer and a time, so cash held too long stands out the same day.

A daily collection sheet by officer, measured against what fell due.

  1. Collected

    Receipt books are issued to each officer by name. Every number is checked, and none can be used twice.

  2. Entered

    A receipt entered late, or out of sequence, needs a manager and a written reason - on the record.

  3. Held

    Cash an officer is holding is recorded against them until it is handed in.

  4. Counted

    Till cash-ups flag variances, which are approved and posted.

  5. Moved

    Cash between branches and strongrooms is tracked in transit.

Ask Swiftly

Ask in plain words. Get the answer from your own data.

Swiftly is built into SwiftlyMFS. Staff ask which loans are late, what is due today or how to do something, and get the answer in seconds, from your own records.

  • Only what their role may see

    Officers hear about their own book, managers about their branch - the same permissions as the rest of the platform.

  • It reads, it never changes

    Swiftly looks things up and explains them. It can't approve, post or change anything.

  • Help from your own manuals

    How-to questions are answered from the manual for the person's role.

  • Under your control

    Set how many questions each person may ask a day, or switch it off.

Asked: Which loans are behind? Swiftly answers: 4 loans are more than 30 days late, with USD 5,764 still owed. The furthest behind is LN-000040 (Kudzai Moyo): 198 days late, USD 1,118.81. Asked: How is the loan book today? Swiftly answers: The USD book is $125,362, up 7.3% on a month ago, with 4.6% of it 30+ days late. In ZWG it is 497,328, up 10.0%, with nothing late.

From first call to go-live

Onboard, operate and oversee on one platform.

  1. STEP 01

    Onboard

    We set up your Country Pack, chart of accounts, products, rates, roles and approval chains with you, with no code, and move your book across.

  2. STEP 02

    Operate

    Officers, tellers and accountants work from one source of truth. Every disbursement, repayment and accrual posts itself, with the right approvals enforced along the way.

  3. STEP 03

    Oversee

    Leadership sees portfolio health, PAR and cash position as they happen, and meets the examiner with the audit trail already assembled.

Get started

See how SwiftlyMFS would run your institution.

Book a 30-minute demo. We'll work through scenarios from how your MFI runs today.

No commitment.